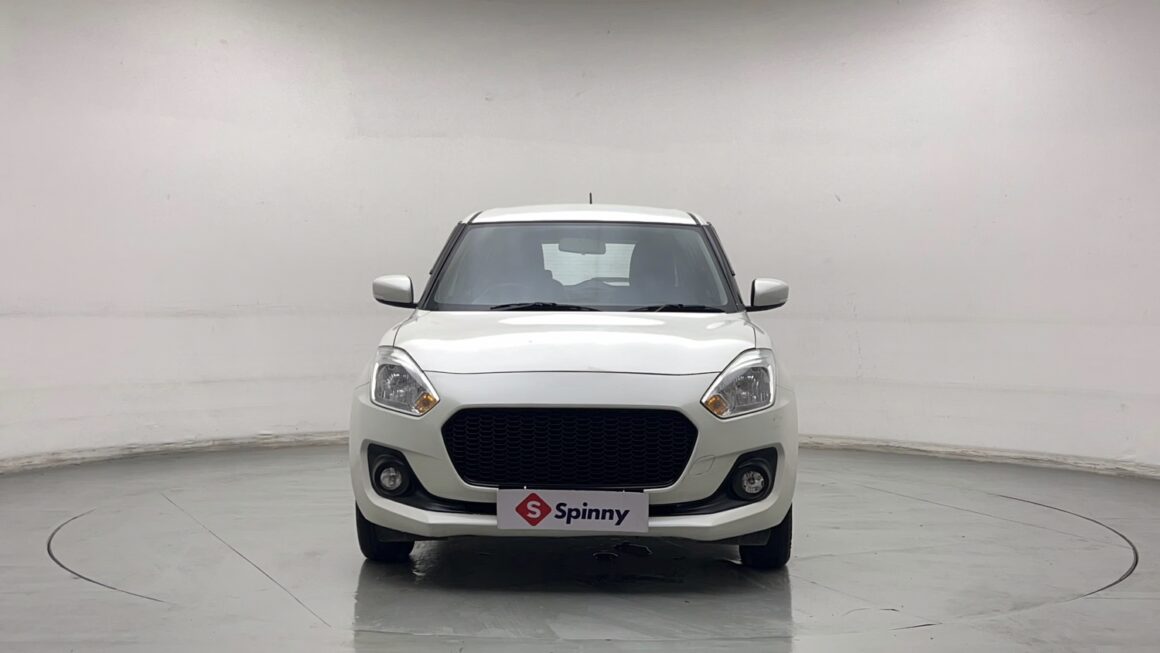
A pre-owned Maruti Swift purchased through an EMI is a good option for those seeking an efficient everyday hatchback without the need to pay the total cost upfront. Its compactness, fuel efficiency and Maruti Suzuki service backup have made it a popular choice for commuting in the city and for family purposes.
Many options are available to choose from based on the year of manufacturing and model. The problem lies in fulfilling the conditions, the cost of the loan and the monthly payments. This article provides guidance on how to compare prices of a used Swift, calculate the EMI, decide the down payment and complete buying the car through Spinny.
Table of Contents
Used Maruti Swift Price Range in India
Two Swifts from the same year can have different prices. A petrol manual with higher kilometres may cost less than an AMT with fewer kilometres, while the variant, ownership history and city also influence the asking price. Start with a price range, then compare the details of individual cars.
These indicative ranges come from selected Spinny petrol Swift listings across cities.
| Model year | Variant/fuel type | Approximate price range (Rs) |
| 2017 | LXi (O), VXi and ZXi; petrol manual | Rs 2.7–4.9 lakh |
| 2020 | VXi and ZXi+; petrol manual / AMT | Rs 4.3–6.4 lakh |
| 2022 | VXi, ZXi and ZXi+; petrol manual / AMT | Rs 5.5–7.4 lakh |
| 2024 | Selected VXi (O), ZXi and ZXi+ variants; petrol AMT | Rs 6.2–8.6 lakh |
Referencing of prices was done on 12th October 2026. These presented price ranges represent the approximate prices and not the actual quotations. The prices and availability may change; additional charges may apply.
Which Swift gives a loan buyer good value?
A well-maintained 2021–2023 petrol Swift is a useful starting point. It belongs to the facelifted third generation, which introduced the Dual Jet Dual VVT petrol engine in 2021. Compared with much older examples, its younger age may also leave more room for a suitable loan tenure, depending on the lender.
If you have decided to go with the VXi model, you can consider the ZXi or ZXi+ based on your budget and if their extra facilities justify the price increase. The features differ from year to year and trim, so make sure to do ample research before you make the final decision.
Check 2024 cars carefully. The fourth-generation Swift launched in May 2024, so a Swift registered that year could belong to either generation. Confirm the manufacturing details and specifications before comparing prices. Browse used Maruti Swift cars on spinny to shortlist options by your city, budget and preferred transmission.
Also Read: Maruti Suzuki Swift Variants Guide: Choose the Best Variant
Used Maruti Swift EMI Calculation
The EMI is simply the amount you pay each month as part of the car finance scheme. It is dependent on the amount of the loan, interest rate charged and repayment duration. A larger down payment will reduce your loan amount, thus reducing the amount of your EMI.
The examples below assume a 20% down payment and 14% annual interest, calculated on a monthly reducing balance. A reducing balance means interest is charged on the outstanding principal as you repay it. These are illustrative car prices, not quotations for specific Swifts.
| Car price | Down payment | Loan amount | Tenure | Approximate EMI |
| Rs 4,00,000 | Rs 80,000 | Rs 3,20,000 | 3 years | Rs 10,937 |
| Rs 4,00,000 | Rs 80,000 | Rs 3,20,000 | 5 years | Rs 7,446 |
| Rs 5,50,000 | Rs 1,10,000 | Rs 4,40,000 | 3 years | Rs 15,038 |
| Rs 5,50,000 | Rs 1,10,000 | Rs 4,40,000 | 5 years | Rs 10,238 |
| Rs 7,00,000 | Rs 1,40,000 | Rs 5,60,000 | 3 years | Rs 19,139 |
| Rs 7,00,000 | Rs 1,40,000 | Rs 5,60,000 | 5 years | Rs 13,030 |
The precise rates, approved loan amounts and available periods are dependent on the lender, applicant’s profile and model of car. These figures do not take into account processing charges, insurance, and other costs.
Look beyond the lower EMI
For the Rs 5.5 lakh example, extending the car loan from three to five years brings the EMI down from about Rs 15,038 to Rs 10,238. That frees up roughly Rs 4,800 each month, but total interest rises from approximately Rs 1.01 lakh to Rs 1.74 lakh. You pay around Rs 72,900 more in interest over the longer period.
Pick a loan term you can afford along with your other payments. A shorter maturity means less money lost on interest, but you need to check whether the higher monthly payment does not leave you short of money for fuel, insurance, upkeep, and any existing obligations.
Use the Spinny used car EMI calculator to compare loan amounts and tenures using your offered rate. Check whether it uses a reducing balance or flat-rate calculation. Identical percentages can produce different borrowing costs under these methods.
Also Read: Car Loan EMI Calculator: Calculate Your Monthly Car Payments
How Much Down Payment Do You Need?
The amount of down payment for your used Swift will depend on the amount of financing approved for your application. Loan to Value (LTV) refers to the percentage of the financing range of the lender’s appraised price of the car. For instance, if you have an LTV of 85% on a Swift valued at INR 5 lakh, you can get funds of INR 4.25 lakh.
Funding limits vary across lenders. For budgeting, compare 80–90% funding to understand what a 10–20% contribution would look like. Your approved funding depends on the lender, your eligibility and the selected car.
| Illustrative funding on a Rs 5 lakh Swift | Loan amount | Contribution towards the car price |
| 80% | Rs 4,00,000 | Rs 1,00,000 |
| 85% | Rs 4,25,000 | Rs 75,000 |
| 90% | Rs 4,50,000 | Rs 50,000 |
There are situations where qualifying buyers can get funding equivalent to 100% of the cost of a vehicle, which depends on the partner offering financing, credit rating and other factors that apply. However, total payment can require additional costs associated with fees, premiums and other purchase expenses.
The selling price and lender’s valuation may also differ. Suppose a Swift costs Rs 5 lakh, but the lender values it at Rs 4.5 lakh. At 85% of that valuation, the loan would be Rs 3,82,500. Your contribution towards the selling price would therefore be Rs 1,17,500, before separately payable charges.
When purchasing an older model of Swift, lenders may set a lower LTV ratio or shorter repayment period. Hence, an affordable car may require a higher down payment than what you are financially prepared for. Be sure to confirm the terms for your chosen Swift first.
A larger down payment reduces your EMI and interest. Keep some savings aside for ownership costs and unexpected expenses after delivery.
Also Read: Maruti Suzuki Swift Running Cost Breakdown: 5-Year Service Cost, Fuel Cost
Step-by-Step Process to Buy a Used Maruti Swift on Loan
Step 1: Set a purchase budget and monthly limit
Figure out the amount that you can spend at once and the monthly payment that will be right for you. In addition to determining your car budget, take into account any existing EMIs and monthly expenses from your household. You should also include the costs of fuel, insurance and service for your Swift.
An EMI of Rs 10,238 covers only the loan payment. Ask for the complete purchase cost so your upfront budget covers expenses outside the approved loan.
Step 2: Shortlist the right Swift on Spinny
Select the city you are in and view the listings of Swift models in that city according to the price, year of manufacture, the type of fuel used and the type of gearbox, such as manual or automatic. When comparing the listed models, consider the mileage, history of the model ownership and the details of inspection.
For a manual, check how the clutch and gear changes feel. If you prefer an AMT, try it in traffic during the test drive to understand its operation. For an older diesel or a CNG example, confirm the fuel details on the RC and suitability for your location before proceeding.
Step 3: Book a test drive and review the car
Make an appointment to test drive your car at the closest Spinny hub or arrange for the car to be brought to your home for the test drive, if this option is available.
Assess braking, steering, air conditioning and comfort during the drive. Listen for unusual noises and ask our team about the inspection report, repairs and service information. Check tyres and upcoming maintenance, since these affect your spending after purchase.
Step 4: Reserve your chosen Swift
After you have chosen the car, go to the website or app and select the booking option. Prior to making payment, check for a refundable deposit, holding period and cancellation policy at the time of booking.
Keep the receipt and confirm how the deposit adjusts against your purchase. Discuss the finance timeline with our team, especially if approval could exceed the reservation period. A booking does not guarantee loan approval.
Step 5: Apply for finance and submit documents
Inform our team that you wish to acquire the Swift on loan. Share details of your preferred down payment and term of the loan. Provide the information required for the finance application. Eligibility is determined by income, type of ownership of the residence, and credit history and score.
The commonly requested documents include:
- PAN card and Aadhaar card.
- Address proof.
- Salary slips or income tax returns, depending on your work profile.
- Six months of bank statements.
More documents may be required depending on the profession, amount of loan requested and lender’s requirements. Make sure that details match on all documents in order to avoid delays.
Step 6: Compare and accept the loan offer
Review the approved second-hand Swift loan before agreeing to it. Check the lender’s name, loan amount, annual interest rate, calculation method, tenure, EMI and total repayment. Ask for a written breakdown of processing fees and other charges.
If you think you would have an early repayment option, check the conditions concerning part payments and foreclosure. Double-check if any applicable insurance or protection product is optional, mandatory, or included in the price quoted by Spinny. You can also independently seek financing for a Spinny car and have one more offer to compare.
Step 7: Complete payment, insurance and delivery formalities
After approval, complete the loan agreement and repayment instructions, and coordinate the down payment and disbursement with the team. Confirm when the first EMI is due and which bank account will be used for repayments.
A financed car is required to be covered by comprehensive insurance. If the listing mentions an existing policy, verify whether the existing insurance will suffice, or you will need to purchase or transfer the coverage to your name. Once the payment and loan details are finalised, check the delivery timeline and keep the invoices, loan documents, and the insurance policy safe with you.
Step 8: Follow the RC transfer and lender entry
We initiate the RC transfer by submitting the required documents to the RTO. You may need to provide documents or attend a verification appointment depending on local requirements. Track the transfer through your Spinny account or app and check the updated details when available.
When the car is financed, the lender’s interest is included in the RC as hypothecation. Once all payments are completed, the borrower must request the lender’s closure documents and carry out removal. By carefully reviewing the Swift and its finance offer, a borrower can begin car ownership fully knowing what to expect both from the car and from their payments.
Also Read: Every Document You Need To Successfully Apply For A Car Loan
Conclusion
Buying a used Maruti Swift on loan works best when you plan for the total cost, not just the EMI. Shortlist a well-maintained Swift, choose a down payment and tenure that fit your monthly budget, and compare the loan offer’s interest, fees and total repayment before you sign. At Spinny, we handle the whole journey with you, from test drive and finance approval to delivery and RC transfer, so you can drive home your Swift with confidence.
Also Read: How to Buy a Used Maruti Suzuki Swift?
FAQs About How to Buy a Used Maruti Swift on Loan
Q. How much is the EMI for a second-hand Swift?
On a ₹4.4 lakh loan at 14% interest, your EMI is about ₹15,038 over 3 years or ₹10,238 over 5 years. You can check your own EMI with our car loan calculator.
Q. How much does a second-hand Maruti Swift cost?
Used Swifts on Spinny start at about ₹2 lakh for older models. 2022–2024 models usually cost ₹5–8.6 lakh, depending on variant, kilometres and city.
Q. Is a second-hand Swift worth buying?
Yes. It’s fuel-efficient, cheap to maintain and backed by Maruti’s wide service network. Every Spinny Swift also comes with a 5-day money-back guarantee and free RC transfer.
Q. Can I buy a used Swift on a bank loan?
Yes. We work with 18 finance partners, and many buyers get approved the same day. Tenures go up to 84 months, and checking your eligibility won’t affect your credit score.
Q. How much down payment do I need for a used Swift?
Most buyers pay 10–20% of the car price, and eligible buyers can get zero down payment. Fees and insurance may still be payable upfront.