Financing a used electric or hybrid car is also possible as lenders offer loans for all types of used cars. The second-hand electric or hybrid car can also be a luxury or regular car. However, there are certain things you must know before financing used hybrid and electric cars. In this green car loan guide, we will cover everything you must know before applying for a used car loan for purchasing pre-owned hybrid or electric cars in India.
Table of Contents
What is a Green Car Loan?
A green car loan refers to the car loan taken for purchasing an eco-friendly car. This applies to loans taken for purchasing plug-in hybrids, EVs, and strong hybrids. When the loan is taken for purchasing any of these used cars, it is referred to as a used green car loan.
Lenders promote purchase of used electric and hybrid cars by providing a discounted interest rate to the borrowers. The reduced interest rate helps reduce the EMI and interest outgo. Remember that used green car loans do not apply for regular cars that run on petrol, diesel, or CNG. They are only applicable for cars with zero emissions. Most banks and Non-Banking Finance Companies (NBFCs) offer used green car loans in India. You can visit their official website or open their app to check the applicable tenure, interest rate range, and other terms and conditions of the loan.
Also Read: What Are Hybrid Cars: Types, Functions, Benefits
Verify These Things Before Financing Pre-Owned EVs & Hybrids
As a smart car buyer, you must know certain things before applying for a pre-owned car loan for purchasing an EV or hybrid car. These things include:
Loan-To-Value Ratio
Loan-To-Value (LTV) ratio refers to the extent of used car price covered through the loan. For EVs and plug-in hybrids, banks may provide up to 100% loan coverage. This means that the entire car value can be paid through the loan amount. However, that also depends on your credit history, CIBIL score, repayment capacity, existing loans, and other factors.
Despite that, financiers usually cover 80 to 100% of the car’s value for EVs and hybrids. The extent of depreciation, used car model, variant, car’s age, running in kms, and overall condition also determines the LTV ratio.
Repayment Term
The loan repayment term or tenure can be selected as per the borrower’s discretion. If the borrower wants to settle the loans early, a shorter tenure can be selected.
For low EMIs, a long tenure would be suitable. However, it would also increase the interest accrued on the principal amount meaning that you would end-up paying more interest if a long tenure is selected. Choose a loan tenure that isn’t too long nor too short because shorter tenure also leads to higher EMIs that can burden your monthly budget.
Loan Interest Rate
Knowing the green car loan interest rate is a must before accepting the loan offer. It is so because the interest rate directly impacts the interest calculated on the principal loan amount. In short, the EMI you will be paying for loan repayment is directly influenced by the used car loan interest rate.
Usually, the used car loan interest rate varies from 12 to 18%. The exact interest rate is evaluated after checking your creditworthiness, income source, existing EMIs, and other factors. The used green car loan may be available at a 0.25 or 0.15% lesser interest rate than the applicable interest rate.
For careful financial planning, you must choose the loan offers wisely. At Spinny Capital, we finance all types of used cars and also match your credit profile with loan offers from different banks and NBFCs. To know the EMIs applicable as per your selected loan amount and tenure, you can use the used car loan EMI calculator.
Loan Eligibility
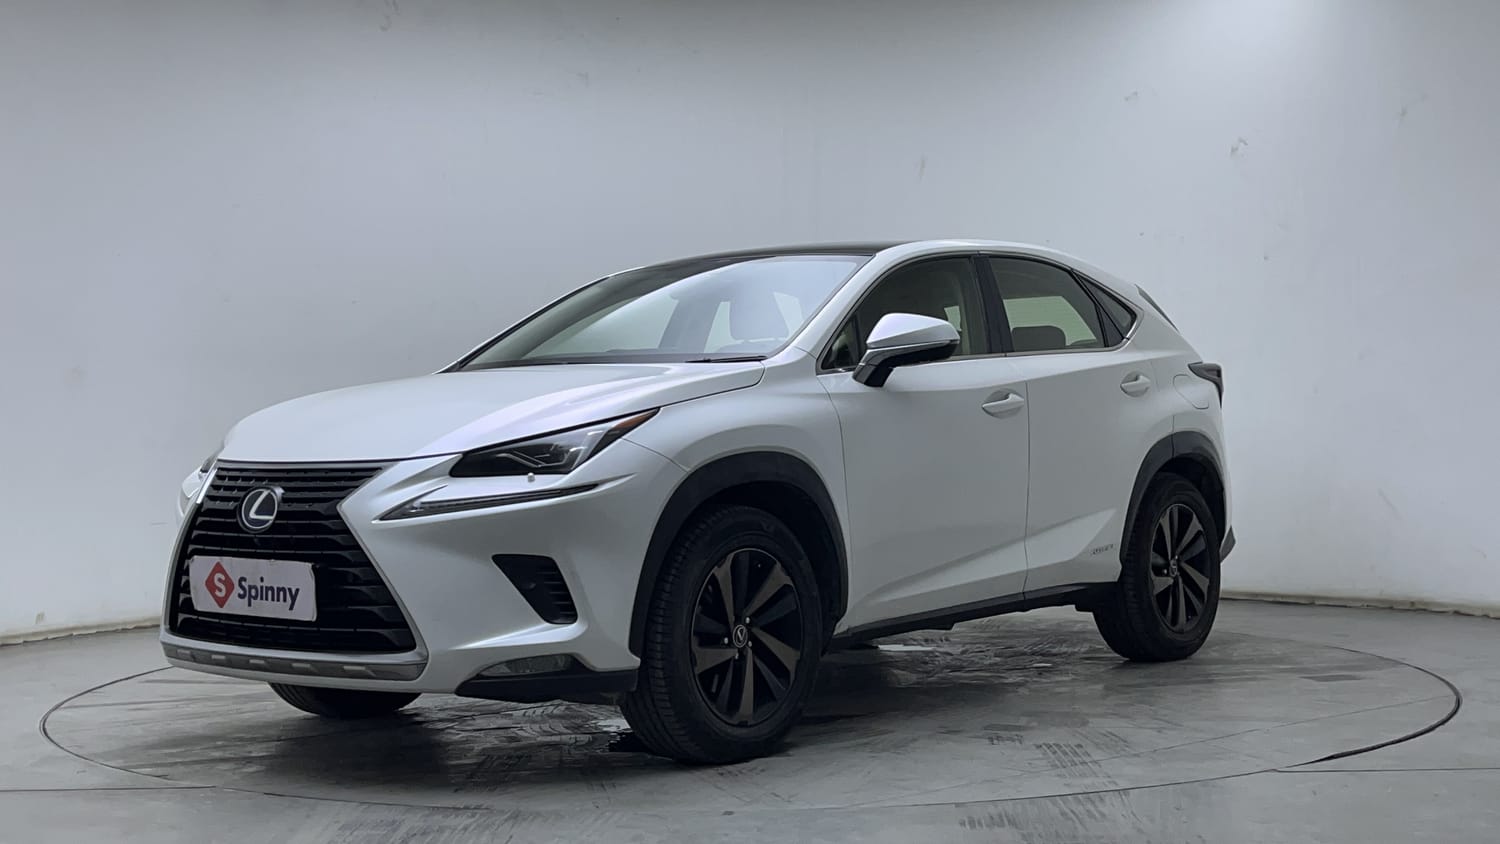
Verifying your loan eligibility is a must before applying for a used hybrid or electric car loan. If you apply without verifying your eligibility and your loan application gets rejected, it will reflect poorly on your credit history and may impact your credit score too. So, always verify your loan eligibility in advance using car loan eligibility calculators and other online tools. The following factors need to be assessed while verifying your used car loan eligibility online:
- Age: Most banks and NBFCs finance used EVs and hybrids if your age bracket falls between 21 and 70. Most lenders consider your age during application while some lenders consider your age during loan maturity to verify your age eligibility for the loan.
- Income: The financier also checks your loan repayment capacity by assessing your annual income. If you are a salaried employee, your salary slips can be used as income proof. If you are self-employed or run a business, your ITR records or business balance sheet can be used as your income proof.
- Debt-To-Income Ratio: Mostly, the debt-to-income ratio is considered while verifying the loan eligibility. If your car loan is less than 30% of your income, your loan will be easily approved. If your debt-to-income ratio exceeds 40% due to pre-existing loans, the financier might disapprove your loan eligibility. Or else, the loan might be approved but at a higher rate of interest. So, keep these things in mind before applying for a used green car loan in India.
- Credit History: The lenders verify your loan eligibility by checking your previous credit history. If there are any bounced EMIs or unsettled loans reflecting in your credit history, your loan eligibility shall not be approved by the lender. While checking your credit history, the financier will also check your credit score as it directly corresponds to your existing credit health.
If the lender considers you eligible for the loan, you shall be asked to submit the required documents along with the loan application. Once the loan is approved, the loan amount shall be disbursed immediately to your account. At Spinny, you don’t have to worry about your loan eligibility at all. We let you verify your used car loan eligibility online and the online verification doesn’t impact your credit score at all.
Special Considerations While Approving Loans for Used EVs and Hybrid Cars
Most banks and finance companies do prefer checking the condition of the used car before granting the loan approval. In case of used EVs and hybrid cars, the following factors play a key role during their in-person inspection:
- Warranty & Health of Battery: The battery health is evaluated using modern battery diagnostic tools such as OBD dongles and third-party apps. The remaining battery life, warranty, and health (calculated in the form of a percentage) are verified by the lender before granting loan approval.
- Age & Service Records: The car’s age is also checked before providing loan approval. If the EV or hybrid car is too old, the lender might not approve the loan. The service records are also evaluated as they determine if the car has been properly maintained by the previous owner or not.
- Resale Value: The financier will also determine the resale value of the car before granting loan approval. Only the valuation provided by certified car valuation agencies are accepted by the lender.
If the lender finds any discrepancy in the car’s overall condition or battery health, the loan application will get rejected. So, you must only purchase verified EVs and hybrid cars.
To purchase verified used EV and hybrid car models, you must trust only verified car platforms such as Spinny. At Spinny, we make the cars go through a rigorous inspection covering 200+ points before certifying them. Also, we provide a detailed inspection report and 1-year warranty with our used cars. This generates trust among the lenders and your loan approval chances get maximised.
Also Read: Finance Your Next Used Electric Car: EV Loan Guide
FAQs About Financing Used Hybrid & Electric Cars – Green Car Loan Guide
Q. How much downpayment is required for used hybrid or EV loans?
A downpayment ranging from 10% to 20% needs to be paid from your end before getting the loan application. This is because banks usually cover 80 to 90% of the car’s value after assessing your loan repayment capacity.
Q. How much discount is offered on the interest rate of used green car loans?
A discount ranging from 0.15 to 0.25% is offered on used green car loans as it varies from one financier to another.
Q. What is the loan tenure applicable for used green loans?
Most lenders offer a tenure ranging from 12 to 60 months for used car loans. However, some lenders might also offer loan tenures up to 84 months depending upon the car’s age and other factors.
Q. What benefits are associated with used green car loans in India?
The banks waive off the processing fee and might also offer a reduced interest rate for used green car loans in India. Some financiers might also waive-off the penalty fees associated with late EMI payment. However, these things vary from one lender to another.
Q. Why is battery health check important for approving used EV or hybrid car loans?
Checking the battery health is important for approving used EV or hybrid car loans because the battery makes up to 50% of the car’s value. So, if the battery is in bad health, the car’s value couldn’t be recovered if the borrower defaults on the loan.